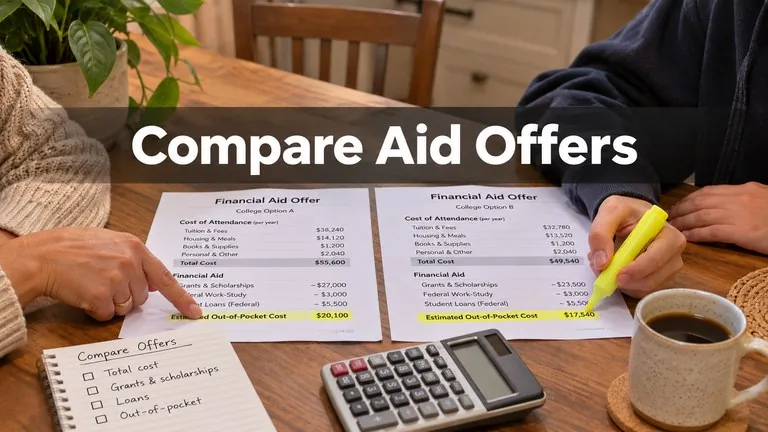
A financial aid award letter, now usually called a financial aid offer, lists the cost of attending a college for one year and the aid that school is offering to cover it. To read it correctly, sort every line into one of three groups: gift aid you never repay (grants and scholarships), self-help aid you earn or repay (work-study and loans), and the cost of attendance. Your real price is the cost of attendance minus gift aid only.
Offers are hard to compare because colleges don’t use one standard format. Some list only tuition and leave out housing. Some add loans into a single “total aid” figure that makes the package look larger than it is. This guide explains each line, shows how to rebuild any offer into a fair comparison, and flags the warning signs worth asking the aid office about before May 1.
The three parts of every aid offer
Whatever the layout, each offer contains the same building blocks.
- Cost of attendance (COA): the school’s full one-year budget, including tuition, fees, housing, food, books, transportation and personal costs.
- Gift aid: federal Pell Grants, state grants, institutional grants and merit scholarships.
- Self-help aid: Federal Work-Study, federal Direct Loans, and sometimes a Parent PLUS loan or a suggested private loan.
Many offers also show your Student Aid Index (SAI), the number from your FAFSA that colleges use to measure financial need. A lower SAI means more need. Financial need is COA minus SAI, and need-based aid can’t exceed that figure.
Grants vs loans vs work-study
The labels on an offer tell you whether the money is a gift, a debt or a paycheck.
| Aid type | Repay? | How it’s paid | 2026-27 details |
|---|---|---|---|
| Federal Pell Grant | No | Credited to your bill each term | Up to $7,395 a year; ineligible if SAI is more than twice the maximum Pell |
| Institutional grant or scholarship | No, but may have GPA or renewal rules | Credited to your bill | Set by each college |
| Federal Work-Study | No, but you must work for it | Paycheck for hours worked, usually every two weeks | Amount is a maximum; not credited to your bill |
| Direct Subsidized Loan | Yes | Credited to your bill | 6.52% fixed; no interest while enrolled at least half time; first-year max $3,500 |
| Direct Unsubsidized Loan | Yes | Credited to your bill | 6.52% fixed; interest builds from disbursement |
| Parent PLUS Loan | Yes, by the parent | Credited to your bill | 9.07% fixed plus 4.228% fee; new borrowers capped at $20,000 a year and $65,000 total per student |
Federal Direct Loans for undergraduates also have a 1.057% origination fee taken out of each disbursement. A dependent first-year student can borrow up to $5,500 total in Direct Loans. The combined limit rises to $6,500 in the second year and $7,500 in the third year and beyond.
Direct costs vs indirect costs
Direct costs are charges the college bills you: tuition, fees, and on-campus housing and meal plans. Indirect costs are estimates for things you pay elsewhere: books, transportation, off-campus rent and personal expenses.
The split affects you in two ways. First, the bill you need to pay by August is based on direct costs only. Second, some colleges leave indirect costs out of the offer entirely, which makes their net price look lower than a school that lists the full COA. If one offer shows a $28,000 cost and another shows $34,000, check whether the first simply skipped books and transportation.
How to compare financial aid offers
Rebuild every offer in the same format before you compare. A spreadsheet with one column per school works well.
- Write down the full cost of attendance for each school. If an offer lists only tuition and housing, find the full COA on the school’s financial aid website.
- Split the COA into direct (billed) costs and indirect costs.
- Add up only grants and scholarships. This is your gift aid.
- Subtract gift aid from the COA. This is your net price, the number to compare first.
- Subtract gift aid from direct costs only. This is what you’ll owe the college on the bill.
- List work-study and each loan separately, with interest rates and fees. Treat these as ways to pay the net price, not as discounts.
- Check the renewal terms for each scholarship: required GPA, credit load and whether the amount stays the same all four years.
- Multiply the net price by four, adding a few percent a year for cost increases, to estimate the full-degree cost.
Example: Aaliyah has two offers. College A lists a $62,000 COA with a $30,000 institutional grant, a $3,000 Pell Grant, $2,500 in work-study and $5,500 in Direct Loans. Its headline says “Total aid: $41,000.” College B lists a $34,000 COA with a $6,000 state grant, a $3,000 Pell Grant, a $2,000 scholarship and $5,500 in Direct Loans, “Total aid: $16,500.” Ignoring loans and work-study, College A’s net price is $29,000 and College B’s is $23,000. College B costs $6,000 less per year, about $24,000 over four years, even though its “total aid” figure is $24,500 smaller.
Red flags to ask about
- A Parent PLUS loan listed as aid. It’s a loan your parent applies for separately, based on a credit check, and it carries a higher rate and fee.
- Private or “alternative” loans included in the package. These aren’t federal aid and should be your last resort.
- A net price of $0 or a “gap” line you don’t understand. Ask how the school calculated it.
- Scholarships that are first-year only, or that require a GPA many students don’t keep, such as 3.5.
- Outside scholarships. Ask how they affect your package. Some colleges reduce loans first, which helps you; others reduce institutional grants.
- No housing or meal plan amount. You’ll still need to pay for both.
Example: Ben’s offer from a private college includes a $15,000 Parent PLUS loan to “complete” the package. His parents would pay 9.07% interest and lose about $634 to the 4.228% fee. Over four years at that level, they’d borrow $60,000, close to the new $65,000 lifetime cap per student for new borrowers. Seeing that line separately, the family decides the school is affordable only if an appeal adds grant money.
Accepting, declining and reducing aid
You don’t have to accept every line. Accept all grants and scholarships. Accept work-study if you want an on-campus job; turning it down doesn’t increase your other aid. For loans, accept subsidized loans before unsubsidized ones, and borrow only what you need to cover the gap after savings and earnings. You can usually accept a lower loan amount than offered and add more later in the year if needed.
First-time federal loan borrowers must complete entrance counseling and sign a Master Promissory Note at StudentAid.gov before funds are paid out. If your family’s finances have changed since the tax year the FAFSA used, or another college made a stronger offer, you can ask the aid office to review your package. That process is called an appeal or a professional judgment review.
Common questions
What is a financial aid award letter?
It’s a college’s offer listing your cost of attendance for one year and the grants, scholarships, work-study and loans available to help pay it. Colleges send it after you’re admitted and have filed the FAFSA and any other required forms. Formats vary by school, so compare offers line by line.
Is work-study taken off my tuition bill?
No. Federal Work-Study is paid to you as wages for hours you work, usually every two weeks. The amount on your offer is the most you can earn. Plan to use it for books and personal costs, not your first tuition payment.
Do I have to accept all the loans in my offer?
No. You can accept, reduce or decline any loan. Accepting grants and scholarships while declining or lowering loans won’t reduce your grant aid. Borrow only what you need after savings and earnings.
Why is my net price different from the net price calculator?
Calculators use the information you entered and the school’s general rules, while the real offer uses your verified FAFSA data and the school’s current budget. Differences in income, assets or household details can change the result. If the gap is large, ask the aid office to explain it.
Does a financial aid offer renew every year?
You must file the FAFSA every year, and your aid can change if your income, household or enrollment changes. Merit scholarships usually renew if you meet the GPA and credit requirements, while need-based grants depend on each new FAFSA. Ask each school how aid typically changes after the first year.
Before you accept an offer
- Rebuild every offer with the full cost of attendance and gift aid listed separately.
- Compare net price first, then the bill you’ll owe after gift aid.
- Read scholarship renewal rules for all four years.
- Accept grants first, then subsidized loans, then unsubsidized loans only as needed.
- Treat Parent PLUS and private loans as separate decisions, not aid.
- Ask about an appeal before May 1 if a school is your top choice but costs more.
Check federal loan rates and limits at StudentAid.gov and the Consumer Financial Protection Bureau’s paying for college tools.
Editorial note: This article is general information, not financial advice. Aid amounts, rates and limits were checked as of November 2026; confirm details with each college’s financial aid office and StudentAid.gov.